
具体描述
在线阅读本书
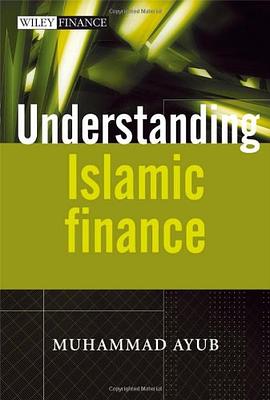
In Understanding Islamic Finance Muhammad Ayub introduces all the essential elements of this growing market by providing an in-depth background to the subject and clear descriptions of all the major products and processes associated with Islamic finance. Key features include: Discussion of the principles of Islamic finance; Introduction to the key products and procedures that International Financial Institutions are using or may adopt to fund a variety of clients ensuring Sharī´ah compliance; Discussion of the role Islamic finance can play in the development of the financial system and of economies; Practical and operational examples that cover deposit and fund management by banks involving financing of various sectors of the economy, risk management, accounting treatment, and working of Islamic financial markets and instruments. This book is not only an important text for all banks and financial institutions entering this particular market with a commitment to building Islamic financial solutions, but is also essential reading for undergraduate and postgraduate students of Islamic finance.
作者简介
MUHAMMAD AYUB is Director Training, Development and Shari’ah Aspects at IIBI, London. Formerly, he was with the State Bank of Pakistan (central bank) where he headed the Islamic Economics Division and Shari’ah Compliance Division as Senior Joint Director in the Research and Islamic Banking Departments. He also served as Head of Islamic Banking at NIBAF, the training wing of SBP. Besides contributing a large amount of material, he has been serving as Master Trainer on theory and practice of Islamic finance.
For last two decades, he has been involved in R&D for facilitating I.B. Industry, Products Development, IB Prudential regulations, Risk management and Shari’ah related controls and audit of Islamic banking institutions. This, along with his association with various Commissions set up from time to time on application of Islamic banking system, has lent him a pragmatic and balanced approach, a prerequisite for presenting such a book.
目录信息
Foreword xix
Preface xxi
Acknowledgements xxv
PART I FUNDAMENTALS 1
1 Introduction 3
1.1 Economic Scenario in the Neoclassical Framework 3
1.2 Conventional Debt: A Recipe for Exploitation 4
1.3 Growth per se May not Lead to Socio-economic Justice 6
1.4 Social Welfare Activities of the States 8
1.5 The Main Culprit 8
1.6 The Need of the Hour 9
1.7 Economics and Religion 10
1.8 Islamic Principles Can Make the Difference 11
1.9 Regulating Trade and Business 13
1.10 Islamic Finance Passing Significant Milestones 15
1.11 Could it Work to Achieve the Objectives? 16
1.12 About this Book 17
2 Distinguishing Features of the Islamic Economic System 21
2.1 Introduction 21
2.2 Islamic Shar?´ah and its Objectives 21
2.3 Why Study Islamic Economics? 25
2.4 Islamic Economics: What should it be? 30
2.5 Paraphernalia of Islamic Economics 32
2.6 Summary 41
3 The Main Prohibitions and Business Ethics in Islamic Economics and Finance 43
3.1 Introduction 43
3.2 The Basic Prohibitions 43
3.3 Business Ethics and Norms 64
3.4 Summary and Conclusion 70
4 The Philosophy and Features of Islamic Finance 73
4.1 Introduction 73
4.2 The Philosophy of Islamic Finance 73
4.3 Debt versus Equity 85
4.4 Islamic Banking: Business versus Benevolence 86
4.5 Exchange Rules 87
4.6 Time Value of Money in Islamic Finance 89
4.7 Money, Monetary Policy and Islamic Finance 90
4.8 Summary 96
PART II CONTRACTUAL BASES IN ISLAMIC FINANCE 99
5 Islamic Law of Contracts and Business Transactions 101
5.1 Introduction 101
5.2 M?l (Wealth), Usufruct and Ownership 101
5.3 General Framework of Contracts 105
5.4 Elements of a Contract 106
5.5 Broad Rules for the Validity of Mu‘?mal?t 110
5.6 W‘adah (Promise) and Related Matters 114
5.7 Types of Contracts 117
5.8 Commutative and Noncommutative Contracts 124
5.9 Conditional or Contingent Contracts 126
5.10 Summary 127
6 Trading in Islamic Commercial Law 129
6.1 Introduction 129
6.2 Bai‘ – Exchange of Values 130
6.3 Legality of Trading 131
6.4 Types of Bai‘ 133
6.5 Requirements of a Valid Sale Contract 133
6.6 Riba Involvement in Sales 142
6.7 Gharar – A Cause of Prohibition of Sales 143
6.8 Conditional Sales and “Two Bargains in One Sale” 144
6.9 Bai‘ al‘Arb?n (Downpayment Sale) 145
6.10 Bai‘ al Dayn (Sale of Debt) 146
6.11 Al ‘Inah Sale and the Use of Ruses (Hiyal) 147
6.12 Options in Sales (Khiyar) 150
6.13 Summary 152
7 Loan and Debt in Islamic Commercial Law 155
7.1 Introduction 155
7.2 The Terms Defined 155
7.3 Illegality of Commercial Interest 157
7.4 Loaning and the Banking System 158
7.5 Guidance from the Holy Qur’?n on Loans and Debts 159
7.6 The Substance of Loans 159
7.7 Repayment of the Principal Only 160
7.8 Time Value of Money in Loans and Debts 160
7.9 Instructions for the Debtor 161
7.10 Instructions for the Creditor 162
7.11 Husnal Qadha (Gracious Payment of Loan/Debt) 162
7.12 Remitting a Part of a Loan and Prepayment Rebate 163
7.13 Penalty on Default 165
7.14 Hawalah (Assignment of Debt) 167
7.15 Security/Guarantee (Kafalah) in Loans 168
7.16 Bai‘ al Dayn (Sale of Debt/Debt Instruments) 172
7.17 Impact of Inflation on Loans/Debts 172
7.18 Summary 174
PART III ISLAMIC FINANCE – PRODUCTS AND PROCEDURES 177
8 Overview of Financial Institutions and Products: Conventional and Islamic 179
8.1 Introduction 179
8.2 What is Banking or a Bank? 179
8.3 The Strategic Position of Banks and Financial Institutions 180
8.4 Categories of Conventional Financial Business 181
8.5 The Need for Islamic Banks and NBFIs 185
8.6 The Issue of Mode Preference 195
8.7 Islamic Investment Banking 199
8.8 Islamic Financial Markets and Instruments 199
8.9 Summary and Conclusion 211
9 Murabaha and Musawamah 213
9.1 Introduction 213
9.2 Conditions of Valid Bai‘ 214
9.3 Murabaha – a Bai‘ al Am?nah 215
9.4 Bai‘ Murabaha in Classical Literature 215
9.5 The Need for Murabaha 216
9.6 Specific Conditions of Murabaha 217
9.7 Possible Structures of Murabaha 220
9.8 Murabaha to Purchase Orderer (MPO) 222
9.9 Issues in Murabaha 229
9.10 Precautions in Murabaha Operations 233
9.11 Musawamah (Bargaining on Price) 234
9.12 Summary 238
10 Forward Sales: Salam and Istisna‘a 241
10.1 Introduction 241
10.2 Bai‘ Salam/Salaf 241
10.3 Benefits of Salam and the Economic Role of Bai‘ Salam 242
10.4 Features of a Valid Salam Contract 243
10.5 Security, Pledge and Liability of the Sureties 249
10.6 Disposing of the Goods Purchased on Salam 250
10.7 Salam – Post Execution Scenarios 252
10.8 Salam-Based Securitization – Salam Certificates/Sukuk 254
10.9 Summary of Salam Rules 255
10.10 Salam as a Financing Technique by Banks 257
10.11 Istisna‘a (Order to Manufacture) 263
11 Ijarah – Leasing 279
11.1 Introduction 279
11.2 Essentials of Ijarah Contracts 280
11.3 General Juristic Rules of Ijarah 281
11.4 Modern Use of Ijarah 287
11.5 Islamic Banks’ Ijarah Muntahia-bi-Tamleek 291
11.6 Summary of Guidelines for Islamic Bankers on Ijarah 298
12 Participatory Modes: Shirkah and its Variants 307
12.1 Introduction 307
12.2 Legality, Forms and Definition of Partnership 308
12.3 Basic Rules of Musharakah 312
12.4 The Concept and Rules of Mudarabah 320
12.5 Mudarabah Distinguished from Musharakah 327
12.6 Modern Corporations: Joint Stock Companies 328
12.7 Modern Application of the Concept of Shirkah 330
12.8 Diminishing Musharakah 337
12.9 Diminishing Musharakah as an Islamic Mode of Finance 339
12.10 Summary and Conclusion 343
13 Some Accessory Contracts 347
13.1 Introduction 347
13.2 Wakalah (Agency) 347
13.3 Tawarruq 349
13.4 Ju‘alah 351
13.5 Bai‘ al Istijrar (Supply Contract) 355
14 Application of the System: Financing Principles and Practices 357
14.1 Introduction 357
14.2 Product Development 358
14.3 The Nature of Financial Services/Business 358
14.4 Prospects and Issues in Specific Areas of Financing 369
14.5 Islamic Banks’ Relationship with Conventional Banks 384
14.6 Fee-based Islamic Banking Services 384
14.7 Summary and Conclusion 386
Appendix: The Major Functions of a Shar?´ah Supervisory Board In the Light of the AAOIFI’s Shar?´ah Standard 387
15 Sukuk and Securitization: Vital Issues in Islamic Capital Markets 389
15.1 Introduction 389
15.2 The Capital Market in an Islamic Framework 390
15.3 Securitization and Sukuk 391
15.4 Summary and Conclusion 412
16 Takaful: An Alternative to Conventional Insurance 417
16.1 Introduction 417
16.2 The Need for Takaful Cover 417
16.3 The Shar?´ah Basis of Takaful 420
16.4 How the Takaful System Works 422
16.5 Takaful and Conventional Insurance Compared 427
16.6 Status and Potential of the Takaful Industry 428
16.7 Takaful Challenges 429
Appendix: Fat?wa (Juristic Opinions) on Different Aspects of Insurance 430
17 An Appraisal of Common Criticism of Islamic Banking and Finance 433
17.1 Introduction 433
17.2 The Common Myths and Objections 433
17.3 Appraisal of Conceptual Criticism 436
17.4 Appraisal of Criticism on Islamic Banking Practice 445
17.5 Conclusion 456
18 The Way Forward 457
18.1 Introduction 457
18.2 Agenda for the Policymakers 457
18.3 Potential, Issues and Challenges for Islamic Banking 461
18.4 Conclusion 479
Acronyms 481
Glossary 485
Bibliography English Sources 497
Arabic/Urdu Sources 503
Suggested Further Readings 505
Index 509
· · · · · · (收起)
读后感
用户评价
对于那些寻求将伦理框架融入严肃商业实践的读者来说,这本书简直是如获至宝。作者的分析极具穿透力,它不仅解释了伊斯兰金融的规则手册,更深入挖掘了这些规则背后的**社会契约论**。我尤其对其中关于**财富循环与社会再分配**的章节印象深刻,作者清晰地阐述了伊斯兰金融体系如何通过强制性的捐赠机制和对投机行为的限制,来构建一个更具韧性的经济结构,这对于当前全球面临的收入不平等问题,提供了一种来自不同文化视角的潜在解决方案。书中对**中小企业融资**的探讨也十分具有现实意义,它展示了在缺乏抵押品担保的传统障碍下,如何通过基于资产支持的融资方式,为实体经济注入活力。这种关注实体经济和人本价值的倾向,贯穿始终。这本书的论述风格是高度**整合性**的,它将历史、法学、经济学和社会学熔于一炉,提供了一个多维度的观察窗口。它不仅仅是在教你如何操作这些工具,更是在培养你运用这些工具时所应具备的道德责任感和宏观视野,读完让人感到既充实又有所启迪,是一本值得反复研读的力作。
这本书的叙事节奏和论证的递进感,使我能够非常顺畅地消化那些原本可能令人望而却步的复杂概念。作者似乎非常清楚读者的知识盲区,并总能在关键时刻插入恰到好处的**历史背景或现实案例**来佐证观点。比如,关于**长期资本形成**的讨论,作者没有直接跳到复杂的工具,而是先回顾了历史上伊斯兰商业网络在丝绸之路上如何运作,这种叙事手法极大地增强了知识的粘性。我个人认为,书中对**风险溢价的重新定义**是全书的一大亮点,它展示了如何将社会效益和道德约束内化为一种“非货币化”的风险回报因子,这在西方金融分析中几乎是空白地带。此外,书中对**保险(Takaful)**模式的讲解,不再是简单地将其等同于互助基金,而是详细拆解了其三方结构和运营机制,清晰地展示了其如何避免传统保险中的赌博性质。这本书的文字风格,不像某些学术著作那样晦涩难懂,它更像是一位极富激情的导师,引导你一步步揭开面纱,理解背后深层的经济逻辑和文化约束是如何相互作用、共同塑造一个金融生态系统的。读后,我对“金融”这个概念的理解被彻底拓宽了。
这本书的深度和广度令人印象深刻,它似乎在金融世界的复杂迷宫中为迷失的旅人指明了方向。我尤其欣赏作者在处理看似矛盾的伊斯兰教法原则与现代金融工具之间的细微差别时所展现出的非凡智慧。书中对风险共担机制(profit-and-loss sharing)的深入探讨,彻底颠覆了我过去对传统借贷模式的刻板印象。作者没有停留在表面现象,而是挖掘到了其核心的伦理基础,这使得即便是对伊斯兰教义了解不深的读者,也能清晰地把握其运作逻辑。例如,关于**穆拉巴哈(Murabaha)**的案例分析,不仅仅是简单地描述了成本加成销售的流程,更是细致地剖析了其如何规避“利息”(Riba)这一核心禁令,同时在商业实践中保持足够的灵活性和吸引力。此外,书中对**伊贾拉(Ijarah)**租赁合同的详尽解析,让我对资产所有权和使用权分离的精妙设计有了全新的认识。这种结构化的叙述方式,使得复杂的金融衍生品概念,如**萨克(Sukuk)**的结构变体,也变得触手可及。总的来说,这本书不仅仅是一本教科书,更像是一份精美的路线图,引导读者穿梭于合规性、商业可行性和神学基础这三重约束之间,是一次令人心悦诚服的知识探险。它成功地将一个常常被误解为“小众”的金融体系,提升到了全球普适的商业智慧高度,其论证的严谨性值得所有金融从业者和研究者借鉴。
读完此书,我的感觉就像是经历了一场对“公平”与“可持续性”的深刻哲学辩论,只不过载体是冰冷的数字和合同条文。作者的笔触极其细腻,尤其是在探讨**财富的社会责任**这一议题时,那种饱含人文关怀的论述,让人在分析金融模型的同时,不断反思资本的最终流向和目的。我特别赞赏其中对**极端贫困与财富集中**的批评视角,这远超出了传统金融教材的范畴。书中对于**古德(Gharar,不确定性)**的界定和管理,被置于风险控制的最高优先级,这与西方金融体系中对“高风险高回报”的追逐形成了鲜明对比,引发了我对现代金融泡沫根源的沉思。作者没有将这种审慎态度描绘成一种教条式的束缚,反而证明了这种内嵌的风险厌恶机制,是如何在历史上帮助伊斯兰金融体系保持相对稳定的。书中对监管框架的描述也十分到位,它揭示了在不同司法管辖区内,如何通过**沙里亚监督委员会(Shari’ah Supervisory Board)**的独立审查,来确保产品设计的“纯正性”。这种双重治理结构本身就极具研究价值。这本书的语言风格更偏向于一种学术性的、带有批判色彩的审视,它挑战了读者既有的金融世界观,促使人们去寻找一种更具道德基础的资本运作模式。
这本书的结构安排堪称教科书级别的典范,但其内容的丰富性远超一般教材的刻板印象。从宏观的**金融稳定理论**到微观的**个人投资组合构建**,作者展现了极强的逻辑跳跃和整合能力。我尤其欣赏作者在不同章节间构建的桥梁——例如,如何将**合伙制(Musharakah & Mudarabah)**的原理,巧妙地应用于大型基础设施项目的融资,而非仅仅局限于小额商业信贷。书中对于**货币理论与价值储存**的讨论,也相当有启发性,它探讨了黄金和实物资产在伊斯兰经济思想中的核心地位,这为理解为什么比特币等去中心化资产在某些圈子中受到青睐提供了历史和理论背景。更令人耳目一新的是,作者将**技术创新**如何影响伊斯兰金融的未来进行了前瞻性分析,例如,移动支付和区块链技术与**Zakat(天课)**管理的结合潜力。这种与时俱进的视角,使得这本书即便是在快速变化的金融科技时代,依然保持着强大的生命力。读起来,仿佛是与一位经验丰富的行业老兵在进行深度交流,他不仅知道“是什么”,更深知“为什么”以及“下一步该怎么做”,行文流畅,论据扎实,对专业术语的解释更是做到了深入浅出。