
具体描述
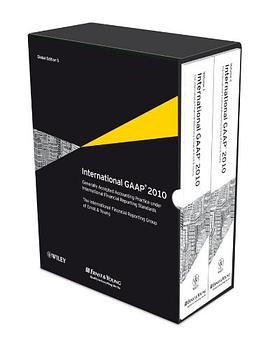
International GAAP 2010 is fully revised and updated in order to:•Deal with all new and amended authoritative pronouncements, including the recent and signifi cant revisions to IAS 1 (Presentation of Financial Statements), IAS 23 (Borrowing Costs), IAS 27 (Consolidated and Separate Financial Statements) and IFRS 3 (Business Combinations)
•Provide insight and guidance on the interpretation and practical application of IFRS from a truly global perspective, based on the experience of the book's authors in dealing with recent day-to-day practical issues
•Explain the many current initiatives that are being pursued by the IASB and IFRIC and that will lead to changes in accounting requirements The impact of IFRS goes beyond financial reporting
The move to International Financial Reporting Standards (IFRS) is the single most important initiative in the financial reporting world, the impact of which stretches far beyond accounting to affect many key decisions companies make. The ongoing development of IFRS requires a constant review of reporting practices. Early assessment of the impact of new and amended standards reduces the pressure of last minute corrections or delays to the accounts. Keeping up to date with the changes and their implications requires professional help
International Financial Reporting Standards are complex and are constantly evolving. Finance professionals face an ongoing challenge to keep abreast of IFRS requirements. It is often difficult to address practical issues by simply referring to the underlying standards. Analysis and interpretation, including worked examples, provides clarity and can save companies a considerable amount of time. Extensive interpretation and practical guidance helps resolve complex financial reporting problems
Providing leading interpretation and practical guidance, every
Chapter contains detailed analysis of how complex financial reporting problems can be resolved appropriately and effectively. International GAAP 2010 demonstrates how difficult practical issues should be approached in the new complex global world of international financial reporting, where IFRS has become the accepted financial reporting system in more than 100 countries. This integrated approach provides a unique level of authoritative material for anyone involved in preparing, interpreting or auditing company accounts, for regulators, academic researchers and for all students of accountancy. The International Financial Reporting Group of Ernst & Young includes financial reporting professionals from around the world. Complex technical accounting issues are explained clearly in a practical working context that enables immediate understanding of the point at issue. International GAAP 2010 is accompanied by numerous worked examples, a comprehensive discussion of the practical issues of the day and the possible alternative solutions available, and hundreds of practical illustrations taken from the actual financial statements of companies that report under IFRSs. In addition, the guidance assists you in understanding today what the impact of tomorrow’s requirements will be. This early assessment of the potential impact of reporting changes can help avoid later problems. Applying the guidance in International GAAP helps ensure a smoother financial reporting and audit process
As a single up-to-date point of reference, International GAAP will help reporting professionals avoid accounting mistakes. Use of International GAAP 2010 throughout the financial year will help finance professionals keep abreast of today’s complex financial reporting requirements and should ensure a smoother financial reporting process.
作者简介
目录信息
读后感
用户评价
这本书的结构设计,说实话,有些许的令人困惑,特别是在章节间的逻辑衔接上。它似乎试图涵盖所有主要的会计领域——从收入确认到租赁、从合并报表到衍生工具——但这种“大而全”的策略,导致了对核心难点处理的碎片化。例如,在处理租赁会计(IAS 17)的部分,对于资本化租赁和经营租赁的区分标准,虽然基本原理阐述清晰,但当涉及到那些模糊地带,如“是否实质上转移了资产所有权风险与报酬”的判断时,书中引用的判例和解释显得不够有力。我期望看到的是更深入的、基于实务挑战的模块化设计,比如专门设立一个“高风险领域判断”章节,集中讨论公允价值层层嵌套的复杂性,或复杂金融工具的套期保值会计中的“有效性测试”等实务操作的痛点。这本书更像是一份严格按照监管机构的章节顺序编排的教材,而不是一本以解决问题为导向的实战手册。这种叙事方式虽然保证了覆盖面的完整性,却牺牲了对核心复杂议题的穿透力。对于一个希望提升自己应对复杂审计挑战能力的人来说,这本书在提供“深度武器”方面是欠缺的,它更像是一套基础的“防御盾牌”,而非能击穿难点的“穿甲弹”。
总的来说,这本书在2010年前后,或许是作为向IFRS过渡期的一个重要里程碑式的参考资料存在。但如果以今天的眼光来审视,它作为一本“长期工具”的价值大打折扣。我特别关注了其中关于“关联方披露”的部分,尽管遵循了IAS 24的要求,但在涉及国有企业或复杂集团架构中,对“实质控制”而非“表面股权”的披露要求,处理得不够尖锐。当时的全球商业环境要求对供应链和控制权的透明度有更高的要求,但书中对于如何运用会计准则来揭示那些隐藏的关联方关系,所提供的分析工具和警示信息相对保守和传统。它似乎更偏向于对既有规则的机械化遵守,而不是鼓励使用者进行批判性思维,去探究商业实质背后的复杂性。一本真正顶尖的国际会计书籍,应该能够激发读者对财务报告背后商业逻辑的深刻理解,引导读者超越合规的最低要求,追求报告的质量和相关性。这本书的贡献更多是“合规性”的保障,而非“卓越性”的催化剂。它稳健有余,却缺乏那种能让人在关键时刻感到醍醐灌顶的洞察力,让人感觉它更像是为那个特定年份服务的“快照”,而不是永恒的“指南针”。
从语言风格和学术严谨性来看,该书的作者群体显然具有深厚的学术背景,但这种学术性有时也转化为一种不易接近的壁垒。大量的引用和对历史背景的追溯,虽然丰富了知识的维度,却也使得文本的节奏显得拖沓和学院派。对于那些已经具备基础会计知识,急需对接国际实务的读者来说,这种过度的学术铺陈显得有些累赘。更让人感到遗憾的是,书中关于“解释性说明”的力度不足。在很多准则的模糊地带,一个好的国际会计指南应该提供清晰的“最佳实践”路径,或者至少明确指出当前全球主要实务界对此的不同处理倾向。然而,这本书更多地停留在“准则如此规定”的层面,对于不同大型会计师事务所(如“四大”)在处理同一问题上可能存在的微妙差异,几乎没有涉及。在国际会计准则的复杂世界里,这些细微的实务操作差异往往是决定性的。这本书未能成功地从“知识的描述者”进化为“实务的引导者”,这使得它在竞争激烈的专业参考书市场中,其独特价值受到了稀释,因为它仅仅是准确地复述了那些可以通过官方渠道获取到的信息,而没有加入足够的、来自一线经验的“提炼和升华”。
这本书的包装和装帧确实令人印象深刻,封面设计简约而不失专业感,那种沉稳的蓝色调和清晰的字体排布,让人一眼就能感受到它内容的权威性和严谨性。然而,当我满怀期待地翻开第一章时,那种预期的深度和广度似乎并未完全展开。我本以为会看到对2010年IFRS准则体系进行彻底的、系统性的梳理和剖析,特别是针对那些在当时引起广泛讨论的复杂公允价值计量和金融工具分类的实务操作难点,能有更为详尽的案例分析和跨司法管辖区的对比视角。例如,关于资产减值测试的预期信用损失模型(当时可能还处于讨论或初步实施阶段),这本书的处理显得有些蜻蜓点水,缺乏那种能让注册会计师在实际工作中立即应用起来的“手把手”指导。更多的是对规则条文的罗列和概括性的解释,对于规则背后的会计理念和管理层判断的灰色地带着墨不多。我期待的是一本能成为我日常工作中的“工具书”,而不是一本仅供回顾历史的参考资料。这种表面上的完整性,掩盖了在实务操作层面深度挖掘的不足,使得这本书更像是一份官方指南的精炼摘要,而非一本能够深刻洞察实践挑战的权威著作。整体来看,它在理论的框架搭建上做得尚可,但在如何将这些框架落地到千变万化的商业场景中,这本书提供的帮助显得有些力不从心,尤其对于那些需要进行复杂跨境交易复杂税务筹划的读者而言,这种浅尝辄止的论述实在难以满足其对精细化知识的需求。
阅读完这本书后,最大的感受是它在“时间性”上的局限性,这在会计准则飞速迭代的领域是致命伤。尽管书名标明是“2010”,但即便以当年的标准来看,它对一些新兴或快速发展的业务模式的反应也显得迟钝。比如,在新兴的SaaS(软件即服务)商业模式收入确认方面,当时业界的争议已经初现端倪,但书中对IFRS 15(当时可能还是预备阶段的准则草案)的讨论几乎是空白或者极其简略,这使得这本书对于当时正在积极拥抱新技术、新商业模式的企业财务部门参考价值大打折扣。我们知道,会计准则的演进往往是滞后于商业实践的,一本优秀的参考书理应预见到未来的趋势并提前进行前瞻性的探讨,指出潜在的实务陷阱和未来可能的变化方向。这本书在这方面显然是保守有余,创新不足。它成功地总结了“过去”和“现在”的准则,但对于“未来”的视野却显得模糊不清。此外,排版上的拥挤和图表使用频率的偏低,也使得冗长的文字描述占据了主导地位,阅读体验并不轻松,这对于需要快速检索特定信息的专业人士来说,无疑增加了查找和理解的负担。一本高效的专业书籍应当是信息密度高且易于消化的,而这本书在信息组织和视觉呈现上,明显没有达到那个时代顶尖专业出版物的标准。