
Random Number Generation and Monte Carlo Methods pdf epub mobi txt 电子书 下载 2026
- 数学
- 金融
- 随机数生成
- 蒙特卡洛方法
- 数值模拟
- 概率统计
- 计算数学
- 算法
- 随机过程
- 科学计算
- 统计建模
- 模拟方法

具体描述
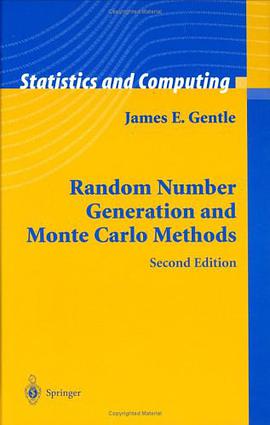
Monte Carlo simulation has become one of the most important tools in all fields of science. Simulation methodology relies on a good source of numbers that appear to be random. These "pseudorandom" numbers must pass statistical tests just as random samples would. Methods for producing pseudorandom numbers and transforming those numbers to simulate samples from various distributions are among the most important topics in statistical computing. This book surveys techniques of random number generation and the use of random numbers in Monte Carlo simulation. The book covers basic principles, as well as newer methods such as parallel random number generation, nonlinear congruential generators, quasi Monte Carlo methods, and Markov chain Monte Carlo. The best methods for generating random variates from the standard distributions are presented, but also general techniques useful in more complicated models and in novel settings are described. The emphasis throughout the book is on practical methods that work well in current computing environments. The book includes exercises and can be used as a test or supplementary text for various courses in modern statistics. It could serve as the primary test for a specialized course in statistical computing, or as a supplementary text for a course in computational statistics and other areas of modern statistics that rely on simulation. The book, which covers recent developments in the field, could also serve as a useful reference for practitioners. Although some familiarity with probability and statistics is assumed, the book is accessible to a broad audience. The second edition is approximately 50% longer than the first edition. It includes advances in methods for parallel random number generation, universal methods for generation of nonuniform variates, perfect sampling, and software for random number generation. The material on testing of random number generators has been expanded to include a discussion of newer software for testing, as well as more discussion about the tests themselves. The second edition has more discussion of applications of Monte Carlo methods in various fields, including physics and computational finance. James Gentle is University Professor of Computational Statistics at George Mason University. During a thirteen-year hiatus from academic work before joining George Mason, he was director of research and design at the world's largest independent producer of Fortran and C general-purpose scientific software libraries. These libraries implement several random number generators, and are widely used in Monte Carlo studies. He is a Fellow of the American Statistical Association and a member of the International Statistical Institute. He has held several national offices in the American Statistical Association and has served as an associate editor for journals of the ASA as well as for other journals in statistics and computing. Recent activities include serving as program director of statistics at the National Science Foundation and as research fellow at the Bureau of Labor Statistics.
作者简介
目录信息
读后感
用户评价
相关图书









本站所有内容均为互联网搜索引擎提供的公开搜索信息,本站不存储任何数据与内容,任何内容与数据均与本站无关,如有需要请联系相关搜索引擎包括但不限于百度,google,bing,sogou 等
© 2026 qciss.net All Rights Reserved. 小哈图书下载中心 版权所有